
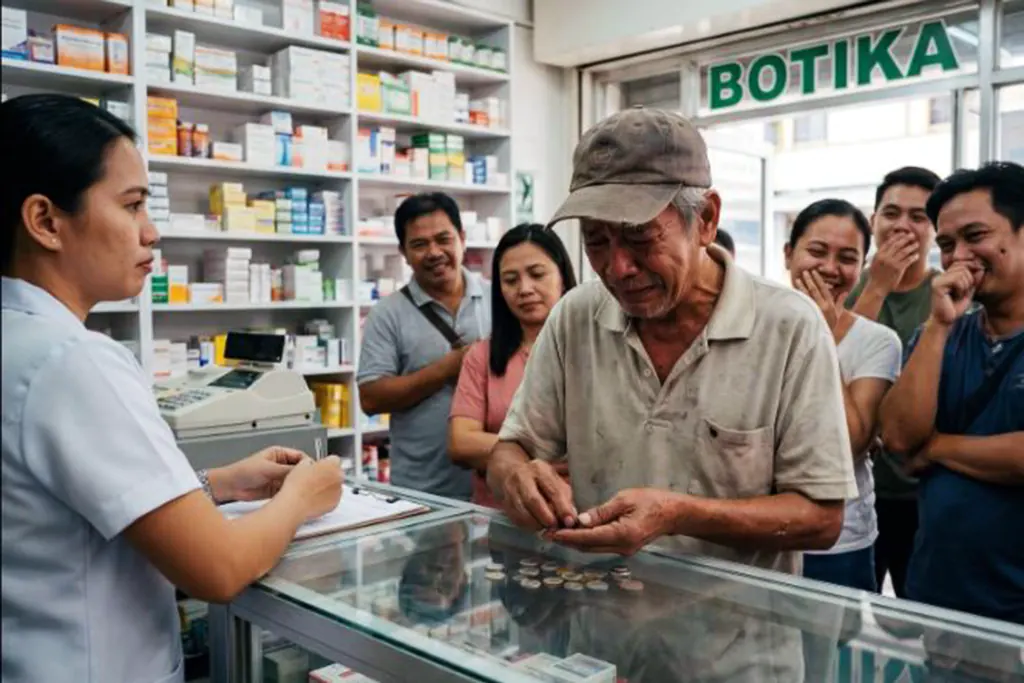
ONLY establishments that actually grant the 20 percent senior citizen discount may claim it as a deduction, subject to the provision governing burden-sharing arrangements for the pharmaceutical sector.
Companies participating in these arrangements must enter into agreements consistent with the guidelines set by the Department of Health (DOH) and said agreements must be properly documented and furnished to the agency.
These changes are contained in the revised and updated 2010 tax rules of the Bureau of Internal Revenue (BIR) on shared drug discounts for senior citizens.
The BIR has revised its 16-year-old tax rules on senior citizen discounts to clarify how pharmaceutical companies, distributors, and retailers can claim tax deductions when they share the cost of discounts on medicines.
The amendments, issued under Revenue Regulations No. 7-2026, address a gap in the original rules issued in 2010, which did not specifically provide for the allocation of tax deductions when the mandatory 20-percent discount was shouldered by different players in the pharmaceutical supply chain, according to the story of the Inquirer.
The change brings the tax treatment of shared discounts in line with the burden-sharing mechanism mandated under Republic Act No. 9994, or the Expanded Senior Citizens Act of 2010, which directed the Department of Health (DOH) to establish guidelines for distributing the cost of discounts among retailers, manufacturers and distributors.
The clarification is particularly relevant where manufacturers, distributors and retailers agree to divide the cost of discounts, since the company selling the medicine to the senior citizen may not ultimately shoulder the entire amount.
Under the revised regulations, the BIR explicitly recognizes pharmaceutical retailers, manufacturers and distributors as establishments covered by these burden-sharing arrangements.
The rules also cover arrangements involving wholesalers-retailers and wholesalers, providing a clearer basis for determining which companies may claim the discount as a deduction from their gross income.
The burden-sharing mechanism, contained in the 2010 law, provided for sharing the financial impact of senior citizen discounts among pharmaceutical supply-chain players.
But the BIR’s implementing regulations issued that year did not specifically explain how the corresponding tax deductions should be divided when more than one company assumed the cost.
Under the amended rules, each company may deduct only the portion of the senior citizen discount it has agreed to shoulder under a burden-sharing agreement.
This means a company cannot claim the entire 20-percent discount as a tax deduction if it bears only part of the cost.
The deduction must correspond to its agreed share of the discount, rather than the full amount granted to the senior citizen at the point of sale.
The requirements establish a documentary basis for determining each participant’s responsibility for the discount and the amount it may claim for tax purposes.
By expressly recognizing burden-sharing agreements, the BIR’s revised rules provide a framework for applying the tax deduction when the cost of a medicine discount is distributed across several businesses instead of being borne entirely by the retailer.